

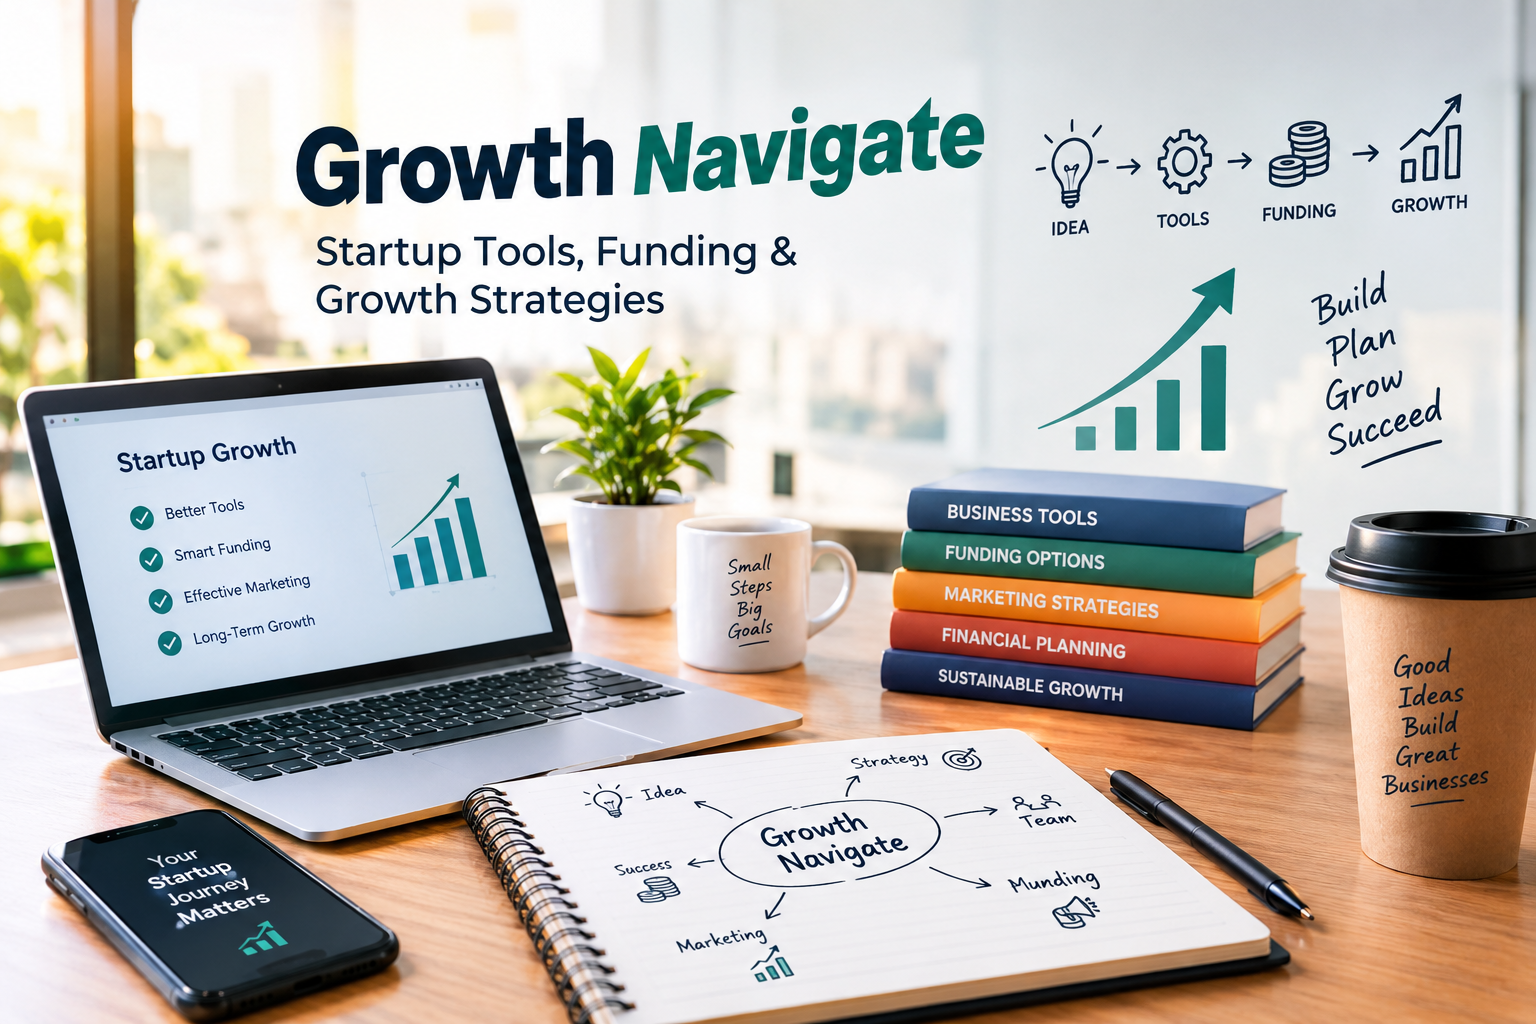
Growth Navigate is about finding a clear direction for building, managing, and expanding a business. Starting a company can be exciting, but turning an idea into a successful business requires more than enthusiasm. Entrepreneurs need practical tools, reliable funding, effective marketing, and a growth plan that matches their goals.
Many startups struggle because they try to do everything at once. They invest in too many tools, spend money without tracking results, or focus on attracting new customers before understanding what their audience actually needs. A more effective approach is to build a strong foundation, make informed decisions, and improve operations step by step.
This guide explores essential startup tools, funding options, marketing strategies, financial planning, and practical ways to achieve sustainable business growth. Whether you are preparing to launch a new venture or looking to improve an existing company, these strategies can help you move forward with greater confidence.
What Is Growth Navigate?
Growth Navigate refers to the process of identifying business opportunities, choosing the right resources, and making strategic decisions that support long-term development. It combines planning, technology, financial management, customer research, and performance measurement.
For startups, growth should not simply mean increasing sales as quickly as possible. Sustainable growth also involves maintaining healthy cash flow, building customer trust, improving products, and creating systems that can handle increasing demand.
A successful growth strategy begins with a few important questions:
- Who are your ideal customers?
- What problem does your product or service solve?
- How will your business generate revenue?
- Which resources are essential during the early stages?
- How will you measure progress?
Answering these questions helps entrepreneurs focus on activities that support real business objectives instead of following every new trend.
1. Build a Strong Foundation for Your Startup
Before investing heavily in marketing or technology, establish a clear business foundation. A well-defined plan makes it easier to manage expenses, communicate your value, and respond to challenges.
Identify Your Target Audience
Understanding your customers is one of the most important steps in building a successful startup. Research their needs, purchasing habits, challenges, and expectations. Customer interviews, surveys, competitor analysis, and online reviews can reveal useful insights.
Instead of trying to serve everyone, concentrate on a specific audience that is likely to benefit from your offer. This makes your marketing more focused and helps you develop products or services that address real problems.
Create a Practical Business Plan
A business plan does not have to be complicated. It should explain what your company offers, who it serves, how it earns money, and what resources it needs.
Include your estimated startup costs, pricing model, marketing approach, sales targets, and expected operating expenses. Review the plan regularly and adjust it when market conditions or customer needs change.
For additional guidance, entrepreneurs can explore the U.S. Small Business Administration’s business guide, which provides resources on business planning, financing, launching, and managing a company.
Test Your Idea Before Expanding
Launching a product on a large scale without testing demand can create unnecessary financial pressure. Start with a minimum viable product, a limited service offering, or a small test campaign.
Collect feedback from early customers and identify what needs improvement. This approach helps you validate your idea before committing significant time and money.
2. Choose the Right Startup Tools
Technology can simplify everyday operations, improve collaboration, and help business owners make better decisions. However, the best tools are those that solve specific problems without adding unnecessary costs.
Project Management Tools
Project management platforms help teams organize tasks, assign responsibilities, and track deadlines. They are especially useful when several people are working on the same project.
Choose a platform that suits your team’s size and workflow. A small startup may only need a simple task board, while a larger team might benefit from project timelines, reporting, and workflow automation.
Accounting and Financial Tools
Accurate financial records help business owners understand income, expenses, outstanding payments, and profitability. Accounting software can reduce manual work and make it easier to prepare financial reports.
Use a consistent system to record transactions and review cash flow. Keep business and personal expenses separate where possible, and retain records needed for tax and compliance purposes.
Customer Relationship Management (CRM)
A CRM system helps businesses organize customer information, track sales conversations, and manage follow-ups. It can prevent promising leads from being forgotten and improve communication with existing customers.
Start with essential features such as contact management, lead tracking, and reminders. More advanced automation can be introduced when your sales process becomes more complex.
Marketing and Communication Tools
Email marketing platforms, scheduling applications, analytics software, and team communication tools can make promotional activities more efficient.
Avoid paying for multiple tools that perform the same function. Begin with the features you actually need, compare costs, and upgrade only when the benefits justify the expense.
3. Explore Funding Options for Sustainable Growth
Funding allows startups to purchase equipment, hire employees, develop products, and reach new customers. However, the right funding source depends on your business model, financial position, growth plans, and willingness to share ownership.
Bootstrapping
Bootstrapping means using personal savings or revenue generated by the business to finance its development.
Advantages:
- You retain greater ownership and control.
- You avoid giving investors a share of the business.
- You can grow according to available resources.
Challenges:
- Growth may be slower.
- Personal financial risk can increase.
- Limited capital may restrict hiring or expansion.
This approach can work well for service-based businesses and startups that can generate revenue without substantial upfront investment.
Business Loans
Loans provide capital that must be repaid according to agreed terms, usually with interest. They may be suitable for businesses with a clear repayment plan and predictable income.
Before borrowing, calculate the total repayment cost and consider how monthly payments will affect cash flow. Compare available lenders and carefully review eligibility requirements, fees, and repayment conditions.
Angel Investors and Venture Capital
Angel investors may provide funding, advice, and industry connections in exchange for an ownership stake. Venture capital firms generally invest in businesses with the potential for significant growth.
These options can help startups scale more quickly, but founders may need to share ownership and decision-making authority. Prepare a convincing business plan, realistic financial projections, and evidence of market demand before approaching investors.
Grants and Startup Competitions
Some government programs, nonprofit organizations, universities, and private institutions offer grants or competitions for eligible businesses. These opportunities vary by country, industry, and applicant requirements.
Research the eligibility criteria carefully and use official sources to verify application details. Do not assume that every grant is available to every startup or that funding is guaranteed.
4. Manage Startup Finances Effectively
A business can attract customers and still struggle if its finances are poorly managed. Financial planning helps founders understand how much money is available, where it is being spent, and how long the business can continue operating at its current pace.
Track Cash Flow
Cash flow measures the money entering and leaving your business. Positive cash flow is important because companies need available funds to pay suppliers, employees, rent, and other operating expenses.
Create a monthly cash-flow forecast and update it as new information becomes available. Consider when customers are likely to pay invoices, not just when sales are recorded.
Separate Essential and Optional Expenses
Prioritize spending that supports product quality, customer service, compliance, and revenue generation. Review subscriptions, advertising campaigns, and operational costs regularly to identify unnecessary expenses.
Keep a financial reserve where possible to manage unexpected costs or periods of slower sales.
Plan for Employee Benefits
As a business expands and begins hiring, employee benefits may become an important part of its operating budget. Small businesses should understand the available options and estimate their costs before making commitments.
For example, entrepreneurs can learn more about dental insurance for small business when researching employee benefits and planning workforce expenses. Evaluating benefits early can help business owners make informed decisions as their teams grow.
5. Develop a Marketing Strategy That Attracts Customers
Marketing helps potential customers discover your business, understand its value, and decide whether to purchase your products or services. A good strategy focuses on the channels your audience actually uses.
Invest in Search Engine Optimization
Search engine optimization (SEO) can help your website appear in relevant search results. Start by researching the questions and terms your potential customers use when looking for solutions.
Create useful content that answers those questions, organize your website clearly, improve page speed, and make sure important pages can be found by search engines. Focus on providing genuine value rather than repeating keywords unnecessarily.
SEO often takes time, so evaluate performance over several months instead of expecting immediate results.
Use Content Marketing
Content marketing allows startups to demonstrate expertise and build trust. Useful content may include blog posts, tutorials, case studies, comparison guides, videos, and frequently asked questions.
Choose topics based on your audience’s challenges. For example, a software startup might publish practical guides that help users solve common workflow problems, while a consulting business could share case studies explaining its approach.
Build a Social Media Presence
Social media can help businesses connect with potential customers, share updates, and gather feedback. Rather than trying to maintain an active presence on every platform, select the channels that best match your audience and resources.
Publish consistently, respond to relevant questions, and use engagement data to understand which topics generate interest.
Test Paid Advertising Carefully
Paid advertising can generate traffic and leads, but spending without a clear measurement plan can quickly consume a startup’s budget.
Begin with a small campaign, define the desired outcome, and track metrics such as cost per lead, conversion rate, and customer acquisition cost. Increase spending only when the campaign demonstrates meaningful results.
6. Measure Growth With Meaningful Business Metrics
Growth Navigate becomes more effective when business owners use reliable data to guide decisions. Tracking too many numbers can create confusion, so focus on a small set of metrics that directly relate to your goals.
Important metrics may include:
- Revenue growth: How much sales income changes over time.
- Customer acquisition cost (CAC): The average cost of acquiring a customer.
- Conversion rate: The percentage of prospects who complete a desired action.
- Customer retention rate: The proportion of customers who continue doing business with you.
- Gross profit margin: The share of revenue remaining after direct costs.
- Cash runway: How long available cash may support the business at its current spending rate.
Review these indicators regularly and investigate unexpected changes. For example, rising sales may appear positive, but if customer acquisition costs are increasing faster than revenue, the business may need to adjust its marketing strategy.
Choose metrics that reflect the current stage of your company. An early-stage startup may prioritize validating demand, while a more established business may focus on profitability, retention, and operational efficiency.
7. Build Systems Before Scaling
Rapid growth can create operational problems when a business lacks clear processes. More customers may mean more orders, support requests, employees, and administrative tasks.
Document repetitive workflows so team members understand how work should be completed. Establish clear responsibilities, create customer support procedures, and automate routine tasks when doing so saves time without reducing quality.
Before expanding into new markets or hiring rapidly, confirm that your existing operations can handle additional demand. Improving a process before scaling it is often more efficient than trying to fix problems after they become widespread.
8. Common Startup Growth Mistakes to Avoid
Even promising businesses can struggle when they make decisions without enough planning. Recognizing common mistakes can help founders protect their resources.
Growing Too Quickly
Expanding before confirming demand or operational capacity can increase expenses and reduce service quality. Grow at a pace that your finances and systems can support.
Ignoring Customer Feedback
Customers often reveal problems that internal teams overlook. Ask for feedback, review complaints, and look for repeated patterns. Use these insights to improve your product or service.
Spending Without Measuring Results
Every major expense should have a clear purpose. Review marketing campaigns, software subscriptions, and hiring decisions to determine whether they contribute to your objectives.
Depending on One Customer or Channel
Relying heavily on one major client, advertising platform, or source of leads can make a business vulnerable to sudden changes. Where practical, develop additional customer relationships and acquisition channels over time.
Neglecting Long-Term Planning
Short-term sales targets are important, but founders should also consider profitability, customer retention, employee needs, and future investment. Sustainable success comes from balancing immediate priorities with long-term business health.
9. A Practical 90-Day Growth Navigate Plan
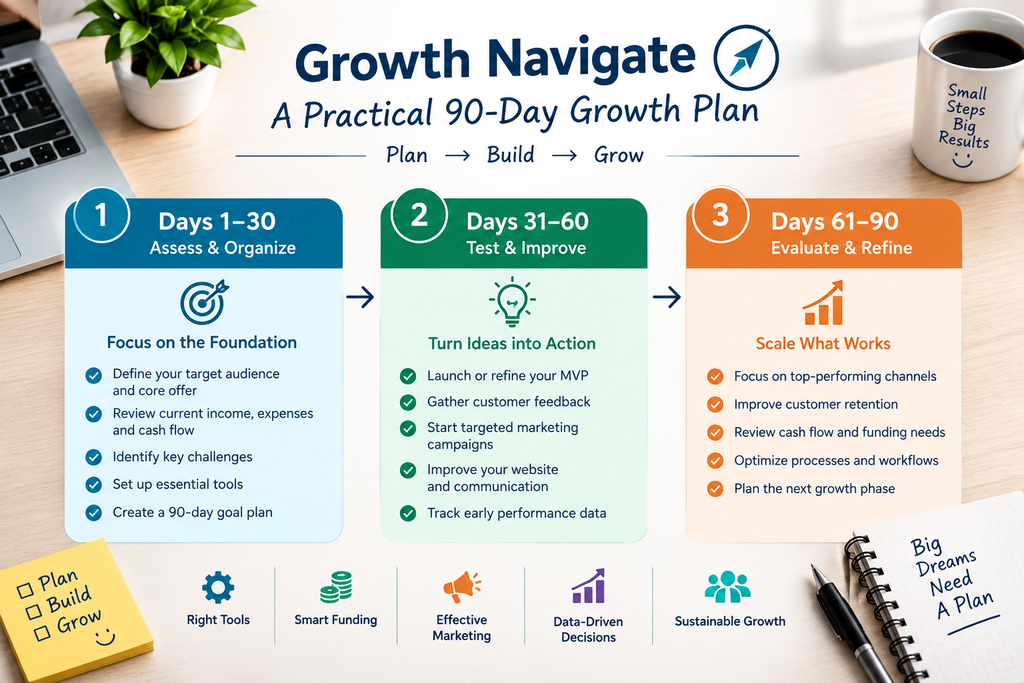
A structured 90-day plan can help turn broad business goals into manageable actions.
Days 1–30: Assess and organize
- Define your target audience and core offer.
- Review current income, expenses, and cash flow.
- Identify the biggest operational or marketing challenges.
- Select essential tools and remove unnecessary subscriptions.
- Establish a small number of measurable goals.
Days 31–60: Test and improve
- Test your product or service with a defined audience.
- Publish helpful content relevant to customer needs.
- Improve your website and customer communication.
- Test a small marketing campaign if your budget allows.
- Collect feedback and review early performance data.
Days 61–90: Evaluate and refine
- Identify the activities generating the strongest results.
- Review conversion rates, customer costs, and cash flow.
- Improve processes that repeatedly cause delays or errors.
- Adjust your marketing and spending priorities.
- Create the next three-month plan based on evidence.
The goal is not to complete every possible task within 90 days. It is to establish a repeatable process for testing ideas, learning from results, and making better decisions.
Frequently Asked Questions
What does Growth Navigate mean for startups?
Growth Navigate describes a strategic approach to developing a startup through planning, appropriate tools, financial management, customer acquisition, and continuous improvement. It helps founders make decisions that support sustainable growth.
Which tools should a new startup use first?
Most startups benefit from basic accounting software, project management tools, customer relationship management, and reliable communication systems. The right selection depends on the company’s size, budget, and daily operations.
What is the best funding option for a startup?
There is no single best option for every business. Bootstrapping may suit founders who want to maintain control, while loans, grants, angel investors, or venture capital may be appropriate in different circumstances. Compare the costs, risks, eligibility requirements, and ownership implications before deciding.
How can a startup grow with a limited budget?
Start by validating demand, understanding your audience, controlling expenses, and focusing on high-value marketing activities. Search engine optimization, useful content, customer referrals, and consistent follow-up may help generate opportunities without requiring a large advertising budget.
How long does it take to see startup growth?
The timeline depends on the industry, business model, competition, available resources, and customer demand. Some businesses generate early sales quickly, while others need months or longer to establish a reliable customer base. Monitor progress and adjust your strategy based on measurable results.
Conclusion
Growth Navigate provides a practical framework for building a startup with purpose and direction. By establishing a strong business foundation, choosing suitable tools, exploring appropriate funding, managing finances, and developing a focused marketing strategy, entrepreneurs can improve their chances of long-term success.
The most effective growth plans are flexible. Customer needs change, new opportunities emerge, and financial conditions can shift. Regularly review your goals, measure the results of your decisions, and improve the processes that support your business.
Start with the actions that matter most, learn from real customer feedback, and expand when your resources and operations are ready. Consistent progress and informed decision-making can help turn a promising business idea into a more sustainable company.